Yes. Buyers living abroad can finance a home in Normandy or Brittany with a French mortgage, and many British buyers choose the region for its short crossing from the UK. Apartments in Deauville and along the Normandy coast also draw buyers from Paris, which supports resale, while lower price points in Brittany can leave a loan under some banks' minimums. On the coast, read the état des risques attached to the sale, which shows flood and coastal-erosion risk.
A mortgage in Normandy or Brittany
A mortgage in Normandy or Brittany works as it does anywhere in France: the 35% repayment ceiling, a 25-year maximum term and purchase costs of 7–8.5% paid from your own funds. What varies is the property, from seaside apartments to farmhouses inland.
Lenders used to the region include Crédit Agricole Normandie's Britline service, which has worked with UK and Irish residents for more than 25 years and offers mortgages through Crédit Agricole regional banks, subject to their approval. National banks with international desks take files here too.
Deauville and the Normandy coast
Deauville, Trouville and Honfleur attract weekend buyers from Paris as well as from abroad, mostly for apartments in a copropriété. That steady demand helps the bank's view of resale. Co-ownership charges, and any works voted for seafront buildings, belong in your budget.
Holiday lets are common on this coast, and banks usually set much of that income aside, counting rent they can verify at around 70%. The Le Meur law of 19 November 2024 has also given communes more power to restrict furnished tourist lets.
Flood and coastal-erosion risk
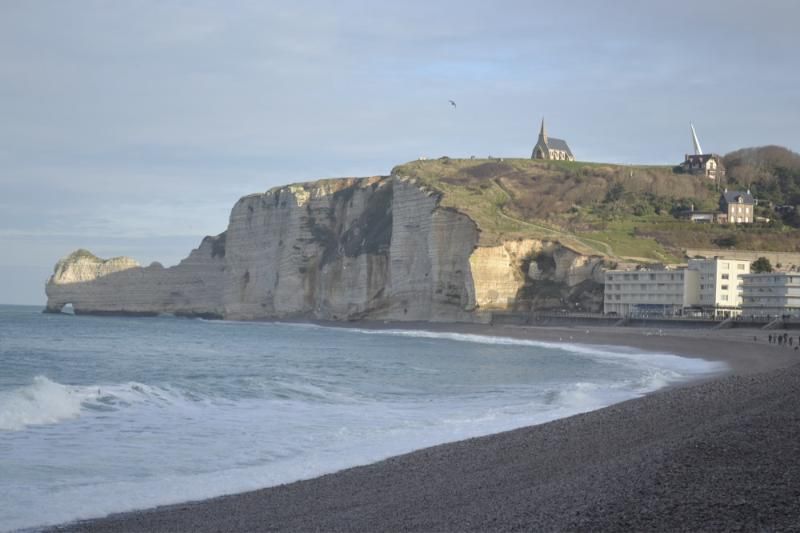
Every sale comes with a state-of-risks report (état des risques) attached to the contract. On these coasts it shows whether the property lies in a flood-risk area, such as a low-lying estuary or river valley, or in a zone exposed to coastal erosion, which affects stretches of cliff and soft shoreline in both regions.
Read it before you sign the compromis. A bank and a home insurer will both take it into account, and a house near a retreating cliff edge can be hard to finance and to resell.
Lower price points in Brittany
Away from the main resorts, Brittany has lower price points, and many foreign buyers look at granite cottages and longères, the long, low farmhouses of the region. A modest price can mean a loan under a bank's minimum for non-residents, commonly €100,000–250,000.
A broker can then search for lenders with lower minimums, or check whether quoted renovation works, which banks can add to the loan, take the amount over the threshold. Isolated rural houses take longer to resell, and some banks lend less on them.
Next steps in Normandy and Brittany
Start with the eligibility check. We pass your request to one broker who places files in the northwest, and you hear back within two working days. French Notaires can find an English-speaking notaire to go through the risk report with you, and the mortgage calculator helps you size the loan before you start viewing.
Your purchase deed is signed before a notaire. French Notaires matches English speakers with a bilingual notaire nearby, free of charge: find a notaire in the region.
Questions
Does Britline lend in Normandy and Brittany?
Britline, run by Crédit Agricole Normandie, works with UK and Irish residents and offers mortgages through Crédit Agricole regional banks, subject to their approval. A broker can tell you which lenders are active for your profile this quarter.
What is the état des risques?
It is the state-of-risks report attached to every sale, showing natural and technological risks such as flooding and coastal erosion. Banks and insurers read it, so check it before signing the compromis.
Can I get a mortgage for a low-priced house in Brittany?
It depends on the loan size. Many banks set a minimum for non-residents, commonly €100,000–250,000, so a small loan may need a lender with a lower threshold or quoted works added to the amount.