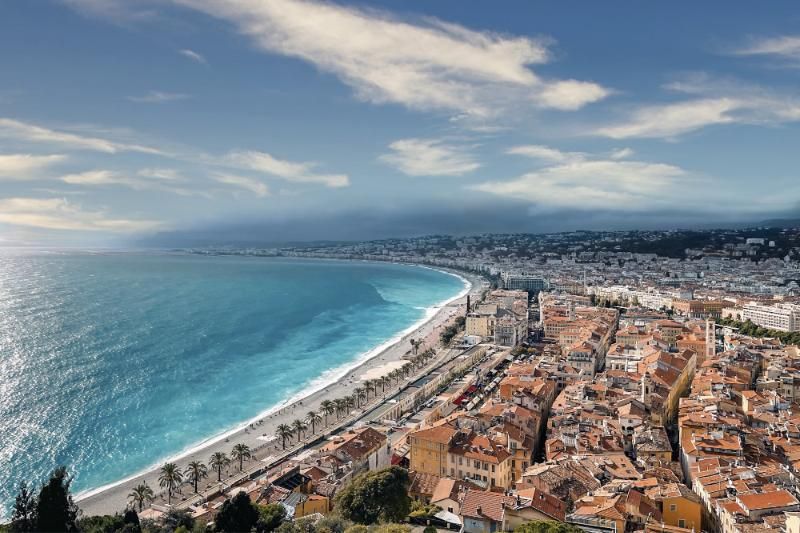
Yes. Buyers living abroad can finance an apartment in Nice with a French mortgage, commonly at 70–80% of the price for strong files from the UK, Ireland, the EU or Switzerland and at 50–70% for residents elsewhere. Purchase costs of 7–8.5% come from your own funds. Since 1 September 2026, letting a second home in Nice to tourists needs a change-of-use authorisation from the first night, capped each year in the main districts, so banks plan the loan without holiday-let income.
What a mortgage in Nice usually finances
A mortgage in Nice for a buyer living abroad nearly always finances an apartment: a flat in a Belle Époque building in the centre, a few rooms in Vieux-Nice, or a sea-view apartment on the slopes of Mont Boron or Cimiez. Villas exist on the hills, but they are a smaller part of the market.
The SeLoger and Meilleurs Agents barometer put the average price of an apartment in Nice at €5,219 per m² on 1 September 2026, and €6,427 per m² for a house. Prices vary a great deal between a side street near the port and a seafront building on the Promenade des Anglais, so the bank's valuer compares your price with recent sales close by.
Lenders here are used to foreign buyers. Notaires de France figures for 2022 put non-resident foreigners at about 7% of sales of existing homes in the Alpes-Maritimes, one of the highest shares in the country.
Holiday lets in Nice now need an authorisation
Under a regulation adopted by the Métropole Nice Côte d'Azur on 22 June 2026 and applied from 1 September 2026, a second home in Nice cannot be let to tourists without a change-of-use authorisation (autorisation de changement d'usage), from the first night. An owner can hold one temporary authorisation, valid for five years and not renewable. In four zones covering Vieux-Nice, the port and Mont Boron, the centre and the west of the city, the number granted each year is capped, and the flat needs an energy rating between A and E.
An earlier version of these rules was suspended by the administrative court in January 2026, and the current one could be challenged too. For your mortgage the answer is the same either way: no bank will treat tourist income on a Nice second home as reliable. Lenders count rent they can verify from a long-term or furnished lease, commonly at around 70%, and the loan has to work on your own income.
If Nice will become your main home
The rules are lighter for a main residence. If you move to Nice and the apartment becomes your home, you can let it to tourists for up to 120 days a year without an authorisation, once it is registered with the city.
If you plan to retire to Nice, banks assess your pensions and savings, and the age at which the loan ends matters. Borrower insurance needs no health questionnaire when the insured amount is at most €200,000 per person and the loan ends before your 60th birthday. Beyond that, expect medical questions and possibly a higher premium. Our guide for retired buyers covers loan terms and insurance in more detail.
Co-ownership votes and running costs
Most Nice apartments sit in a copropriété (co-ownership). Since the Le Meur law, co-owners can ban tourist lets of second homes by a two-thirds vote rather than unanimously, where the building's rules already reserve the flats for residential use. The Conseil constitutionnel upheld this in March 2026. Read the co-ownership rules and the minutes of recent general meetings before you sign, both for any ban and for works voted on roofs, facades or lifts.
Nice applies the maximum 60% surcharge on the council tax for second homes, on the city's share of the tax. Add it, the property tax and the co-ownership charges to your budget. The bank checks that repayments stay within 35% of your net income, and it also looks at what is left to live on once the loan is paid.
An English-speaking mortgage broker for Nice
Through the eligibility check, we introduce you to one English-speaking broker who places files for buyers in Nice and along the coast. Matching is free. Ask for a loan condition of at least 60 days in the compromis, since a non-resident file usually takes six to ten weeks to reach an offer. For the purchase itself, French Notaires in Nice can introduce you to an English-speaking notaire. Our Côte d'Azur guide covers villas, private banks and SCIs, and the mortgage calculator shows repayments and purchase costs.
Your purchase deed is signed before a notaire. French Notaires matches English speakers with a bilingual notaire nearby, free of charge: Notaires in Nice.
Questions
Can a UK resident get a mortgage for an apartment in Nice?
Yes. French banks commonly lend 70–80% of the price to UK residents with strong files, provided total repayments stay within 35% of net income. Purchase costs of 7–8.5% come from your own funds.
Can I rent my Nice apartment on Airbnb when I am not using it?
Only with a change-of-use authorisation from the city, required from the first night for a second home since 1 September 2026. The number granted each year is capped in the main districts, so do not count on it when you plan the purchase.
How much deposit do I need to buy in Nice as a non-resident?
Plan for 20–30% of the price if you live in the UK, Ireland, the EU or Switzerland and 30–50% elsewhere, plus purchase costs of 7–8.5%. The exact figure depends on your income, your other loans and the lender.
Is there extra council tax on a second home in Nice?
Yes. Nice applies the maximum 60% surcharge to the city's share of the council tax on second homes. Budget for it alongside the property tax and the co-ownership charges.